Table of Contents
CICT 3Q 2026 Business Updates demonstrated why CapitaLand Integrated Commercial Trust remains one of the premier Singapore REITs for long-term income investors. As the largest REIT position in my stock portfolio, CICT currently accounts for 8.07% of my stock portfolio. Based on CICT 3Q 2026 Business Updates, the trust delivered another quarter of resilient operating performance, healthy rental reversions, strong portfolio occupancy and continued value creation through acquisitions, asset enhancement initiatives and strategic capital recycling.
CICT unit price closed at S$2.28 on 30 October 2026. After reviewing the latest business update, I remain positive on the REIT’s ability to generate sustainable distributions and long-term capital growth.
Strong Financial Performance in 9M 2026
A key highlight from the CICT 3Q 2026 Business Updates was the REIT’s continued ability to grow earnings despite an environment of elevated interest rates and ongoing portfolio reconstitution.
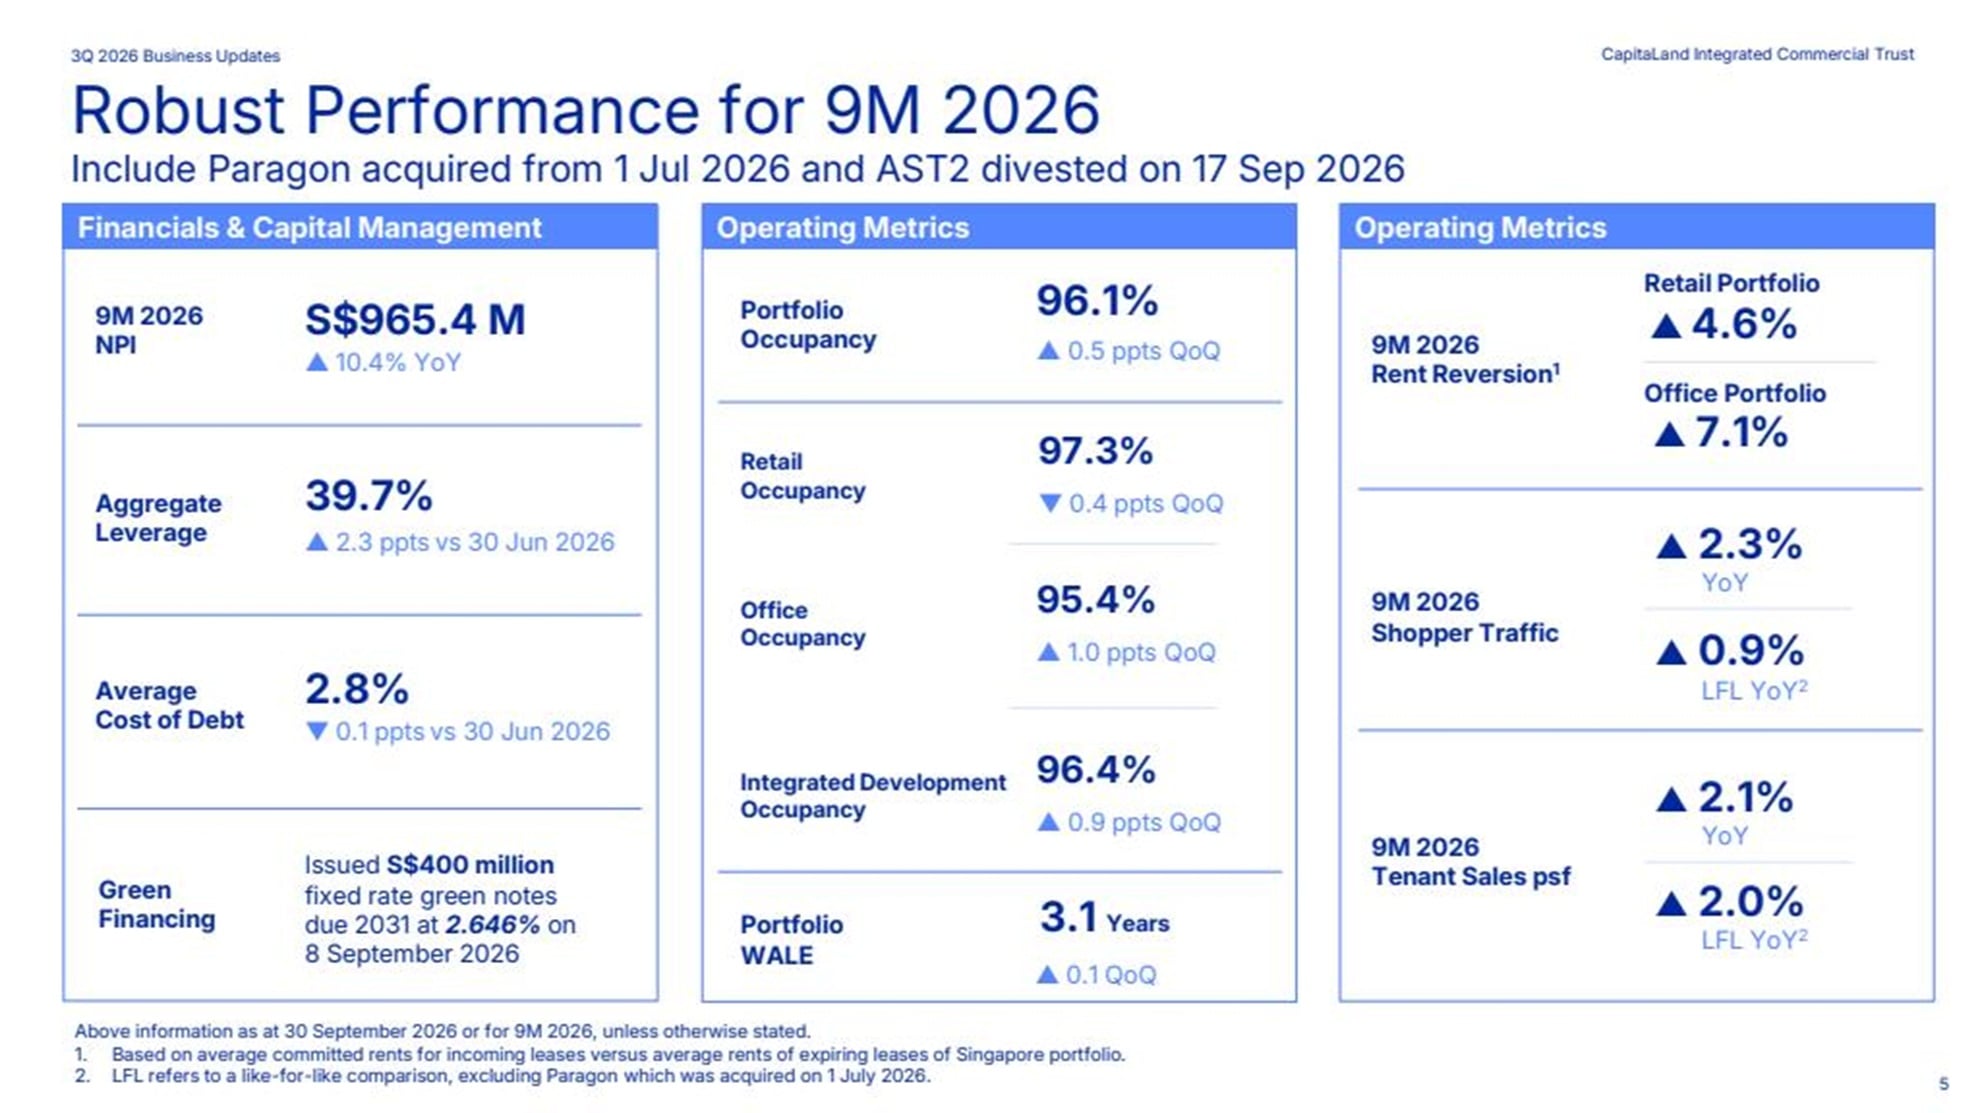
For the first nine months of 2026, gross revenue increased 10.0% year-on-year to S$1.31 billion while net property income (NPI) rose 10.4% year-on-year to S$965.4 million. The stronger performance was primarily driven by contributions from Paragon, Gallileo and the acquisition of the remaining stake in CapitaSpring, partially offset by the divestments of Bukit Panjang Plaza and Asia Square Tower 2.
The momentum was also visible during the third quarter. Gross revenue for 3Q 2026 increased 15.0% year-on-year to S$464.5 million while NPI rose 13.8% year-on-year to S$334.9 million.
These results demonstrate management’s ability to grow earnings while actively reshaping the portfolio. Rather than simply holding assets indefinitely, CICT continues to recycle capital into higher-return opportunities while maintaining operational stability.
Portfolio Occupancy Remains Exceptionally Strong
One of the most attractive qualities of CICT has always been the resilience of its diversified portfolio. The latest CICT 3Q 2026 Business Updates once again showcased the quality of its assets.
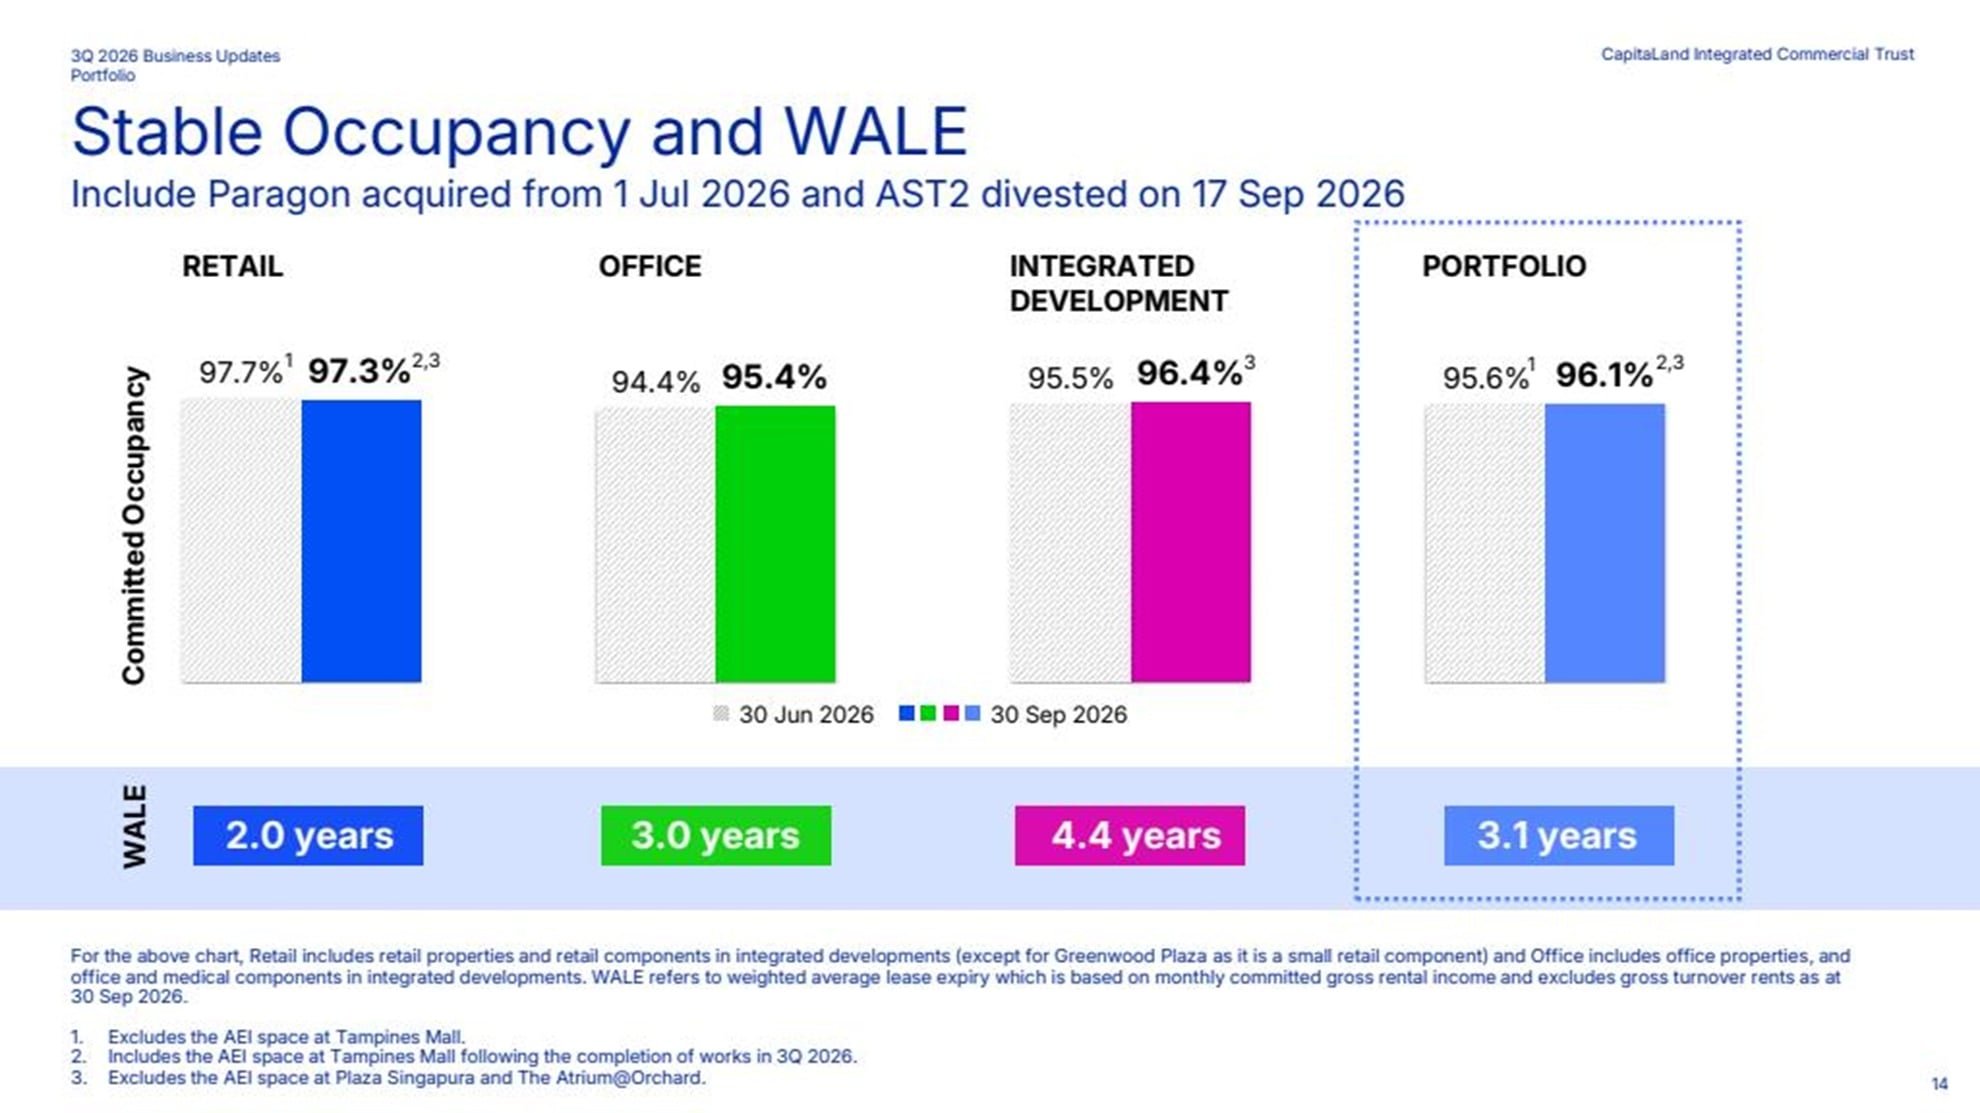
Portfolio occupancy improved to 96.1% as at 30 September 2026, up from 95.6% in the previous quarter. Retail occupancy remained extremely healthy at 97.3%, office occupancy increased to 95.4% and integrated developments achieved occupancy of 96.4%.
The portfolio’s weighted average lease expiry (WALE) stood at 3.1 years, providing income visibility and stability for unitholders.
High occupancy rates across all segments are a clear indication that tenants continue to value CICT’s prime locations and quality assets. In a competitive commercial property market, consistently maintaining occupancy above 95% is a noteworthy achievement.
Positive Rental Reversions Continue Supporting Organic Growth
Rental reversion remains one of the most important metrics for REIT investors because it reflects management’s pricing power and ability to grow income organically.
The CICT 3Q 2026 Business Updates showed encouraging rental reversions across both retail and office segments. Retail rent reversion came in at 4.6% while office rent reversion registered an even stronger 7.1%.
Within the retail portfolio, downtown malls delivered rental reversions of 4.5% while suburban malls achieved 4.6%. The ability to secure positive rent reversions across multiple asset categories indicates healthy tenant demand and the attractiveness of CICT’s portfolio.
Management also expects rent reversions to remain in the mid-single-digit range in the coming quarters. This should provide a meaningful source of organic earnings growth without relying solely on acquisitions.
Retail Portfolio Shows Continued Resilience
The retail portfolio remains a core contributor to CICT’s earnings and continues to perform well despite ongoing economic uncertainties.
For 9M 2026, shopper traffic increased 2.3% year-on-year while tenant sales per square foot rose 2.1% year-on-year. On a like-for-like basis excluding Paragon, shopper traffic increased 0.9% and tenant sales improved 2.0%.
Several retail trade categories delivered positive growth. Food and beverage sales increased 1.6%, fashion and accessories rose 1.5% while beauty and health recorded growth of 0.8%.
These numbers suggest that consumers continue to spend across CICT’s mall portfolio and that tenant businesses remain healthy. This should support future rental growth and occupancy stability.
Tampines Mall Asset Enhancement Initiative Delivers Early Success
One of the more exciting developments highlighted in the CICT 3Q 2026 Business Updates was the completion of the Tampines Mall asset enhancement initiative.
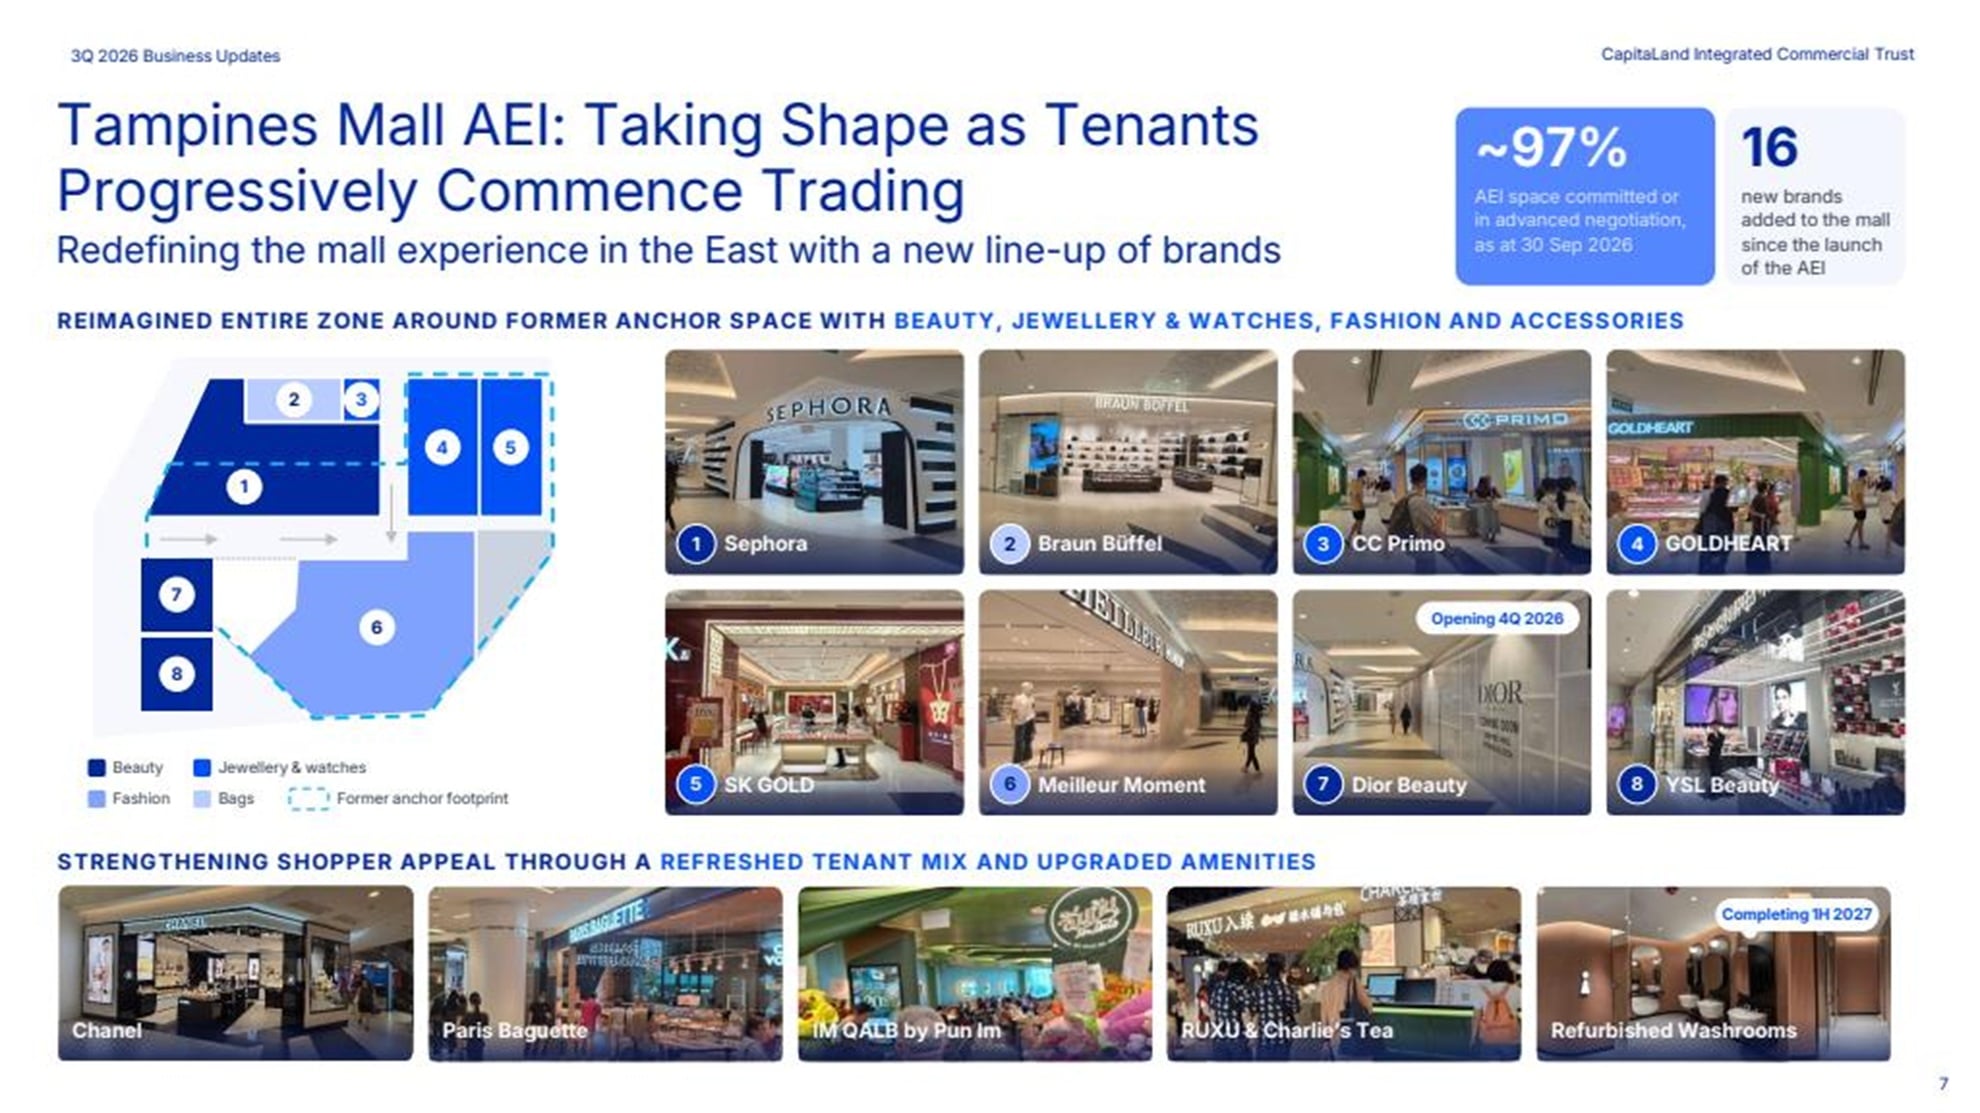
The approximately S$24 million project was completed in 3Q 2026 and is expected to generate returns of around 7%. As at 30 September 2026, approximately 97% of the enhanced space had already been committed or was in advanced negotiations.
The enhancement project introduced 16 new brands and transformed the former anchor space into a modern retail zone featuring beauty, jewellery, watches, fashion and lifestyle concepts.
This demonstrates management’s ability to unlock additional value from existing assets and improve the customer experience without acquiring new properties. Such initiatives can drive both tenant sales growth and higher rental income over time.
Office Portfolio Continues To Improve
The office segment also delivered encouraging results in the quarter.
Office occupancy improved to 95.4% from 94.4% previously while average office rents continued to trend upwards. Leasing activity remained healthy with approximately 490,000 square feet of office leases secured during the quarter.
New office leases were mainly driven by demand from engineering, information technology and telecommunications, as well as banking, insurance and financial services sectors.
Several major lease renewals and new leases were successfully completed, reinforcing demand for well-located prime office assets despite global economic uncertainties.
The ongoing recovery in office fundamentals and limited future office supply in key business districts could provide additional support for rental growth going forward.
Active Capital Recycling Strengthens Future Growth Prospects
CICT continues to demonstrate disciplined capital allocation through strategic divestments and reinvestment opportunities.
A significant milestone during the quarter was the completion of the divestment of Asia Square Tower 2 on 17 September 2026. The transaction generated approximately S$2.45 billion in net sales proceeds and achieved an exit yield of 3.0%.
The divestment creates substantial financial flexibility and allows management to redeploy capital into higher-yielding investments and development opportunities.
One such opportunity is the Hougang Central mixed-use development. The commercial component is expected to comprise approximately 300,000 square feet of net lettable area with an estimated development cost of around S$1.1 billion. Management expects the project to generate a yield exceeding 5% upon completion around 2030 to 2031.
This project has the potential to become another meaningful contributor to CICT’s earnings in the future.
Balance Sheet Remains Well Managed
While acquisitions and investments have increased leverage, the balance sheet remains healthy and manageable.
Aggregate leverage increased to 39.7% as at 30 September 2026 from 37.4% in the previous quarter. Total borrowings stood at S$11.1 billion.
Importantly, the weighted average cost of debt declined slightly from 2.9% to 2.8%, which is a positive outcome given the prevailing interest rate environment. About 76% of borrowings remain on fixed interest rates, helping to reduce earnings volatility.
The REIT also issued S$400 million of green notes due in 2031 at a fixed interest rate of 2.646%, further enhancing the debt maturity profile and sustainability credentials of the trust.
CICT maintains strong investment-grade credit ratings of A3 from Moody’s and A- from S&P, providing confidence that the REIT can continue accessing capital markets at competitive rates.
Debt Maturity Profile Reduces Refinancing Risk
One of the strengths of CICT is its disciplined approach to managing refinancing risk.
The debt maturity profile remains well distributed across multiple years with no excessive concentration in any single year. This provides flexibility and reduces the risk associated with refinancing large amounts of debt during periods of market stress.
In addition, sustainability-linked financing and green funding now represent approximately S$8.4 billion, or more than 70% of total borrowings. This positions CICT favourably as lenders and investors place increasing importance on sustainability-linked financing structures.
Sustainability Leadership Continues To Differentiate CICT
Sustainability remains a key pillar of CICT’s long-term strategy.
During 2026, the REIT maintained its five-star GRESB rating and improved its score from 91.7 to 93.5 points. CICT was also recognised as both Global Sector Leader and Regional Sector Leader within the diversified office and retail category.
Furthermore, 100% of the portfolio by gross floor area is now green-rated. Strong ESG performance not only benefits the environment but also supports tenant attraction, operational efficiency and access to sustainable financing.
For long-term investors, sustainability leadership can contribute meaningfully to asset competitiveness and portfolio resilience.
My Thoughts on CICT 3Q 2026 Business Updates
After reviewing the CICT 3Q 2026 Business Updates, my investment thesis remains unchanged.
CICT continues to deliver steady operational execution across its retail, office and integrated development portfolio. Occupancy remains high, rent reversions are positive, tenant sales continue to grow and management is successfully enhancing asset quality through redevelopment and asset enhancement initiatives.
The acquisition of Paragon is already contributing positively to earnings while future projects such as Lot One Shoppers’ Mall, Capital Tower, Plaza Singapura, The Atrium@Orchard and the Hougang Central development provide additional growth opportunities.
Although leverage has increased slightly following recent acquisitions and investments, the balance sheet remains healthy, refinancing risk is well managed and the cost of debt remains competitive.
With CICT units closing at S$2.28 on 30 October 2026, investors continue to gain exposure to one of Singapore’s highest-quality commercial REITs. Supported by prime assets, experienced management and multiple growth drivers, CICT remains one of the strongest blue-chip REITs available for investors seeking sustainable passive income and long-term wealth accumulation.
For me personally, CICT continues to deserve a meaningful allocation and currently represents 8.07% of my stock portfolio.