Table of Contents
Keppel DC REIT 3Q 2026 Results demonstrated why this data centre REIT continues to be one of the most closely watched Singapore REITs among income investors. As a long-term investor myself, Keppel DC REIT currently makes up 5.08% of my stock portfolio based on the amount invested, making it one of my meaningful positions in the Singapore REIT sector.
At a Keppel DC REIT Share Price of S$2.13, investors are naturally asking whether the REIT’s growth trajectory remains intact after another quarter of expansion and whether the Keppel DC REIT dividend can continue growing in the years ahead.
The latest Keppel DC REIT 3Q 2026 Results suggest that management continues to execute well on both organic growth and acquisitions. Strong rental reversions, increasing distributable income, growing exposure to hyperscale customers and the completion of the Tokyo Data Centre 4 & 5 acquisition give investors several reasons to be optimistic.
Keppel DC REIT 3Q 2026 Results At A Glance
The headline numbers from the Keppel DC REIT 3Q 2026 Results were impressive.
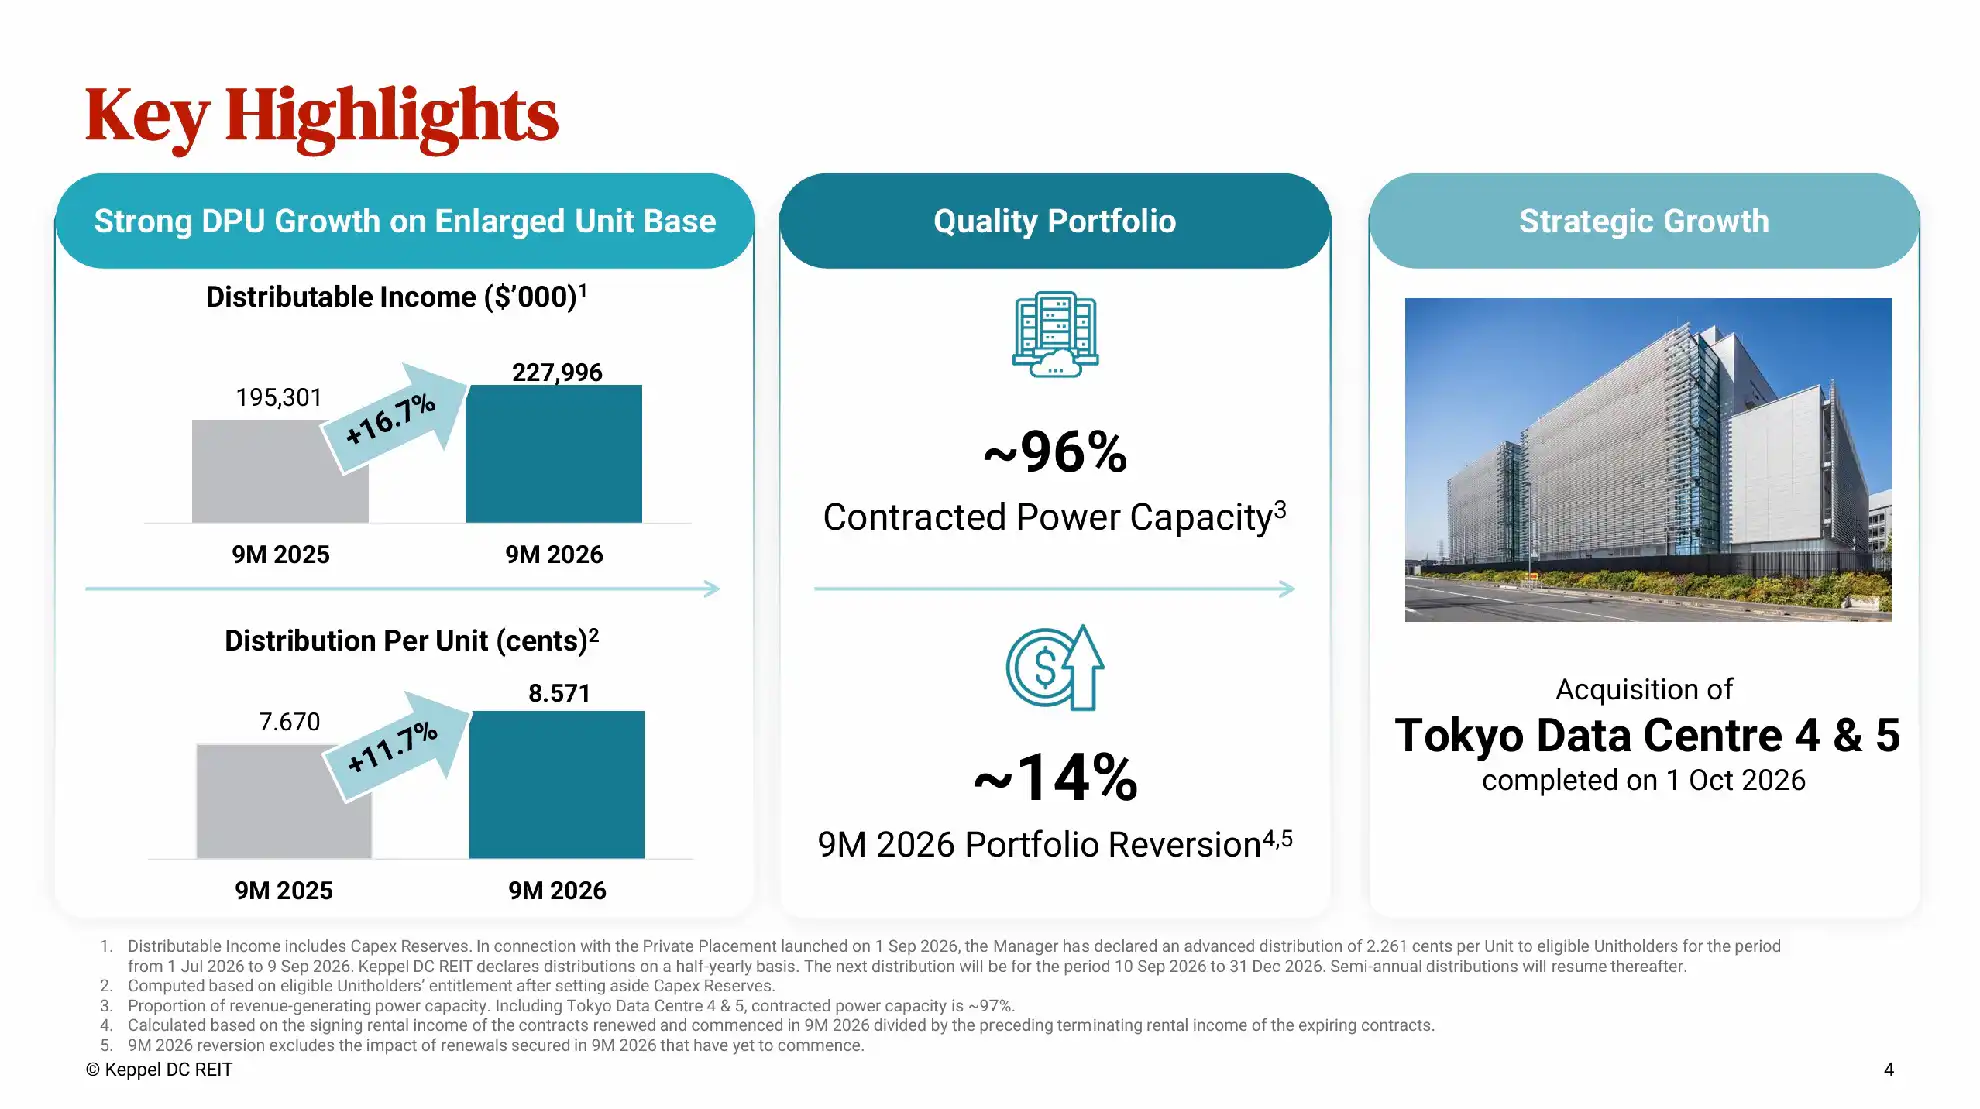
For the first nine months of 2026, gross revenue increased 13.3% year-on-year to S$365.3 million. Net property income grew 13.1% to S$316.8 million. More importantly for income investors, distributable income rose 16.7% to S$228.0 million.
The most significant figure was the growth in distribution per unit. DPU increased from 7.670 cents to 8.571 cents, representing year-on-year growth of 11.7%.
Considering that the enlarged unit base following the September 2026 private placement has already been taken into account, the Keppel DC REIT 3Q 2026 Results indicate that operational performance remains robust.
For investors focused on passive income, the steady growth in Keppel DC REIT dividend distributions remains one of the biggest attractions of the REIT.
Why The Keppel DC REIT Dividend Continues To Grow
One key reason behind the increasing Keppel DC REIT dividend is the combination of organic rental growth and strategic acquisitions.
Management highlighted that positive rental reversions and escalations contributed meaningfully to earnings growth. Portfolio rental reversion for the first nine months of 2026 was approximately 14%, suggesting strong leasing momentum across the portfolio.
The data centre industry continues benefiting from structural growth drivers such as cloud computing, artificial intelligence, digital transformation and increasing enterprise demand for computing power. As demand remains high and supply remains constrained in many markets, landlords like Keppel DC REIT have been able to secure favorable rental terms.
The Keppel DC REIT 3Q 2026 Results show that management is successfully translating these industry tailwinds into higher distributable income and ultimately a stronger Keppel DC REIT dividend.
Tokyo Data Centre Acquisition Is A Major Growth Driver
One of the most important developments in the Keppel DC REIT 3Q 2026 Results was the completion of the Tokyo Data Centre 4 & 5 acquisition.
This acquisition represents approximately S$1.37 billion in value and significantly increases Keppel DC REIT’s exposure to the attractive Japanese data centre market.
Several features of the acquisition stand out.
The assets have 100% occupancy, providing immediate income stability. The properties also enjoy annual rental escalation of approximately 2.8%. Importantly, management indicated that existing rents are more than 30% below market levels, creating embedded upside over time.
The acquisition is expected to be DPU accretive by approximately 2%.
This is exactly the kind of acquisition investors want to see. It is not merely asset accumulation for the sake of growth. Instead, it appears capable of enhancing future Keppel DC REIT dividend distributions while strengthening portfolio quality.
For long-term investors, this acquisition could become one of the most important catalysts arising from the Keppel DC REIT 3Q 2026 Results.
Strong Portfolio Fundamentals Remain Intact
Beyond acquisitions, the underlying portfolio continues performing well.
Occupancy stood at 93.0%, improving from the previous quarter. Contracted power capacity reached approximately 96%, demonstrating strong customer demand.
The portfolio maintains a weighted average lease expiry of 6.5 years based on lettable area. Such long lease durations provide a high degree of earnings visibility.
A major positive from the Keppel DC REIT 3Q 2026 Results is the quality of customers occupying its facilities.
The REIT derives more than 70% of rental income from internet enterprise customers, including hyperscalers. These are among the largest and strongest balance-sheet operators globally.
In an era where artificial intelligence and cloud infrastructure spending continue accelerating, customer quality becomes increasingly important. The concentration in high-quality technology tenants supports the investment case and future Keppel DC REIT dividend sustainability.
AI Demand Could Support Long-Term Growth
One of the themes highlighted in the Keppel DC REIT 3Q 2026 Results is the growing role of artificial intelligence.
The report discussed expectations that AI workloads could account for approximately 50% of Asia-Pacific data centre demand by 2030. At the same time, large global technology companies continue investing heavily in AI infrastructure.
This creates a favorable backdrop for data centre landlords.
Unlike many traditional property sectors where growth depends largely on economic cycles, data centres benefit from structural demand drivers. Businesses are generating more data than ever before. AI applications require large amounts of processing power. Cloud adoption continues growing globally.
As a result, the long-term outlook underpinning the Keppel DC REIT dividend remains attractive.
The combination of constrained power supply, lengthy grid connection timelines and expanding AI demand potentially allows operators to maintain pricing power.
Capital Management Remains Reasonable
A review of the Keppel DC REIT 3Q 2026 Results would not be complete without assessing the balance sheet.
Aggregate leverage stood at 36.2% as of 30 September 2026. On a pro-forma basis including the recently completed Japanese acquisition financing, leverage would be approximately 38.8%.
While leverage has increased due to acquisitions, it remains within a range that many Singapore REIT investors would consider manageable.
Interest coverage ratio was reported at 6.5 times. This remains healthy despite higher borrowing costs associated with acquisition financing.
Average cost of debt remained relatively low at 2.6% for the first nine months of 2026.
Another positive takeaway from the Keppel DC REIT 3Q 2026 Results is that nearly 70% of debt is fixed-rate. Management also expects this proportion to rise into the high 80% range after Japanese interest-rate swaps become effective.
This should help limit exposure to future interest-rate volatility.
Diversification Across Countries And Customers
The Keppel DC REIT portfolio now spans 27 data centres across 10 countries.
Approximately 87.4% of assets are located in Asia-Pacific, while the remainder is located in Europe.
Singapore remains the largest market, accounting for around 51.9% of assets, while Japan represents 28.6%.
This geographical diversification provides some protection against country-specific risks while allowing investors to participate in multiple high-growth data centre markets.
Customer diversification is another strength highlighted by the Keppel DC REIT 3Q 2026 Results.
The portfolio serves about 80 customers across internet enterprises, IT services, telecommunications firms, financial institutions and corporate clients.
Although hyperscalers form an important customer segment, the overall tenant base remains broad enough to reduce concentration risks.
Is The Keppel DC REIT Share Price Attractive At S$2.13?
With the Keppel DC REIT Share Price trading at S$2.13, valuation becomes an important question.
The market appears to recognize the quality of the portfolio and its growth prospects. Keppel DC REIT has historically traded at premium valuations relative to many traditional REIT sectors because of its exposure to structural technology trends.
The latest Keppel DC REIT 3Q 2026 Results likely reinforce that premium positioning.
Investors are not simply buying warehouses filled with servers. They are buying exposure to cloud computing, artificial intelligence, digital infrastructure and long-term technology spending growth.
Whether the Keppel DC REIT Share Price is attractive ultimately depends on an investor’s objectives.
Income-focused investors may appreciate the growing Keppel DC REIT dividend stream.
Growth-oriented investors may find the AI-related demand story compelling.
Meanwhile, conservative investors may prefer waiting for larger market pullbacks before increasing their positions.
Personally, since Keppel DC REIT already accounts for 5.08% of my portfolio by invested amount, I view it as an important contributor to my long-term dividend income strategy.
My Overall Thoughts On Keppel DC REIT 3Q 2026 Results
The Keppel DC REIT 3Q 2026 Results were encouraging on multiple fronts.
Revenue growth remained strong. Net property income continued increasing. Distributable income grew at a faster pace than revenue. DPU rose by double digits despite the enlarged unit base.
Management also continues executing growth initiatives through strategic acquisitions while maintaining a relatively healthy balance sheet.
The addition of Tokyo Data Centre 4 & 5 enhances portfolio quality and gives investors greater exposure to one of Asia’s most attractive data centre markets.
Most importantly, the factors supporting future Keppel DC REIT dividend growth remain intact. Long lease terms, strong customer quality, rising AI demand and favorable data centre industry fundamentals all contribute to a constructive long-term outlook.
While investors should remain aware of risks such as higher interest rates, customer concentration and future competition, the latest Keppel DC REIT 3Q 2026 Results suggest that the REIT remains well-positioned for future growth.
Pros And Cons Of Investing In Keppel DC REIT
Pros
- Strong DPU growth of 11.7% in the latest Keppel DC REIT 3Q 2026 Results.
- Distributable income increased 16.7% year-on-year.
- Growing Keppel DC REIT dividend supported by operational improvements and acquisitions.
- Exposure to long-term growth themes such as AI, cloud computing and digital transformation.
- Acquisition of Tokyo Data Centre 4 & 5 provides additional growth potential.
- Portfolio rental reversion of approximately 14% demonstrates pricing power.
- Healthy occupancy of 93.0% and contracted power capacity of approximately 96%.
- Long WALE of 6.5 years provides earnings visibility.
- Diversified portfolio spanning 27 data centres across 10 countries.
- Debt profile remains manageable with substantial fixed-rate borrowings.
Cons
- Aggregate leverage has increased due to recent acquisitions.
- Higher finance costs could pressure future earnings if interest rates remain elevated.
- Premium valuation means the Keppel DC REIT Share Price may be sensitive to growth disappointments.
- Dependence on large technology and hyperscale customers.
- Data centre sector remains capital intensive and requires continuous investment.
- Currency fluctuations may affect overseas earnings.
- Future distributions still depend on successful integration and execution of acquired assets.