Singapore Treasury Bills (T-Bills) are short-term government securities issued by the Singapore government to meet its financing needs.
They are sold at a discount and mature in either 6 months or 1 year, making them a popular option for parking short-term cash.
T-Bills vs Singapore Savings Bonds vs Fixed Deposits
| Feature | T-Bills | Singapore Savings Bonds | Fixed Deposits |
|---|---|---|---|
| Issuer | Singapore Government | Singapore Government | Individual banks |
| Tenure | 6 months or 1 year | Up to 10 years, redeemable anytime | Typically 3-24 months |
| Early withdrawal | Not applicable (fixed term) | Yes, any month, no penalty | Usually penalised or forfeits interest |
| Rate structure | Fixed for the term, set at auction | Step-up rates over 10 years | Fixed for the term |
| Minimum investment | S$1,000 | S$500 | Varies by bank, often S$1,000-S$20,000+ |
| Can use CPF-OA / SRS | Yes | CPF-OA only (not SRS) | Some banks allow CPF/SRS |
For a detailed comparison of how these three options stack up, see my Singapore Savings Bond versus Savings Account versus Fixed Deposits breakdown, or my Best Fixed Deposit Rates in Singapore guide if you’re weighing T-Bills against bank deposits specifically.
Recent T-Bill Yields
6-month T-Bill cut-off yields have swung notably through 2026, dipping to around 1.30% in August before jumping to 1.92% per annum at the 24 September 2026 auction (BS26119F), the highest level since early in the year, as yields tracked shifts in US Federal Reserve rate expectations. For the latest individual auction results, see my most recent T-Bill auction breakdown, or check the full list of past auctions below.
How to Buy Singapore Treasury Bills
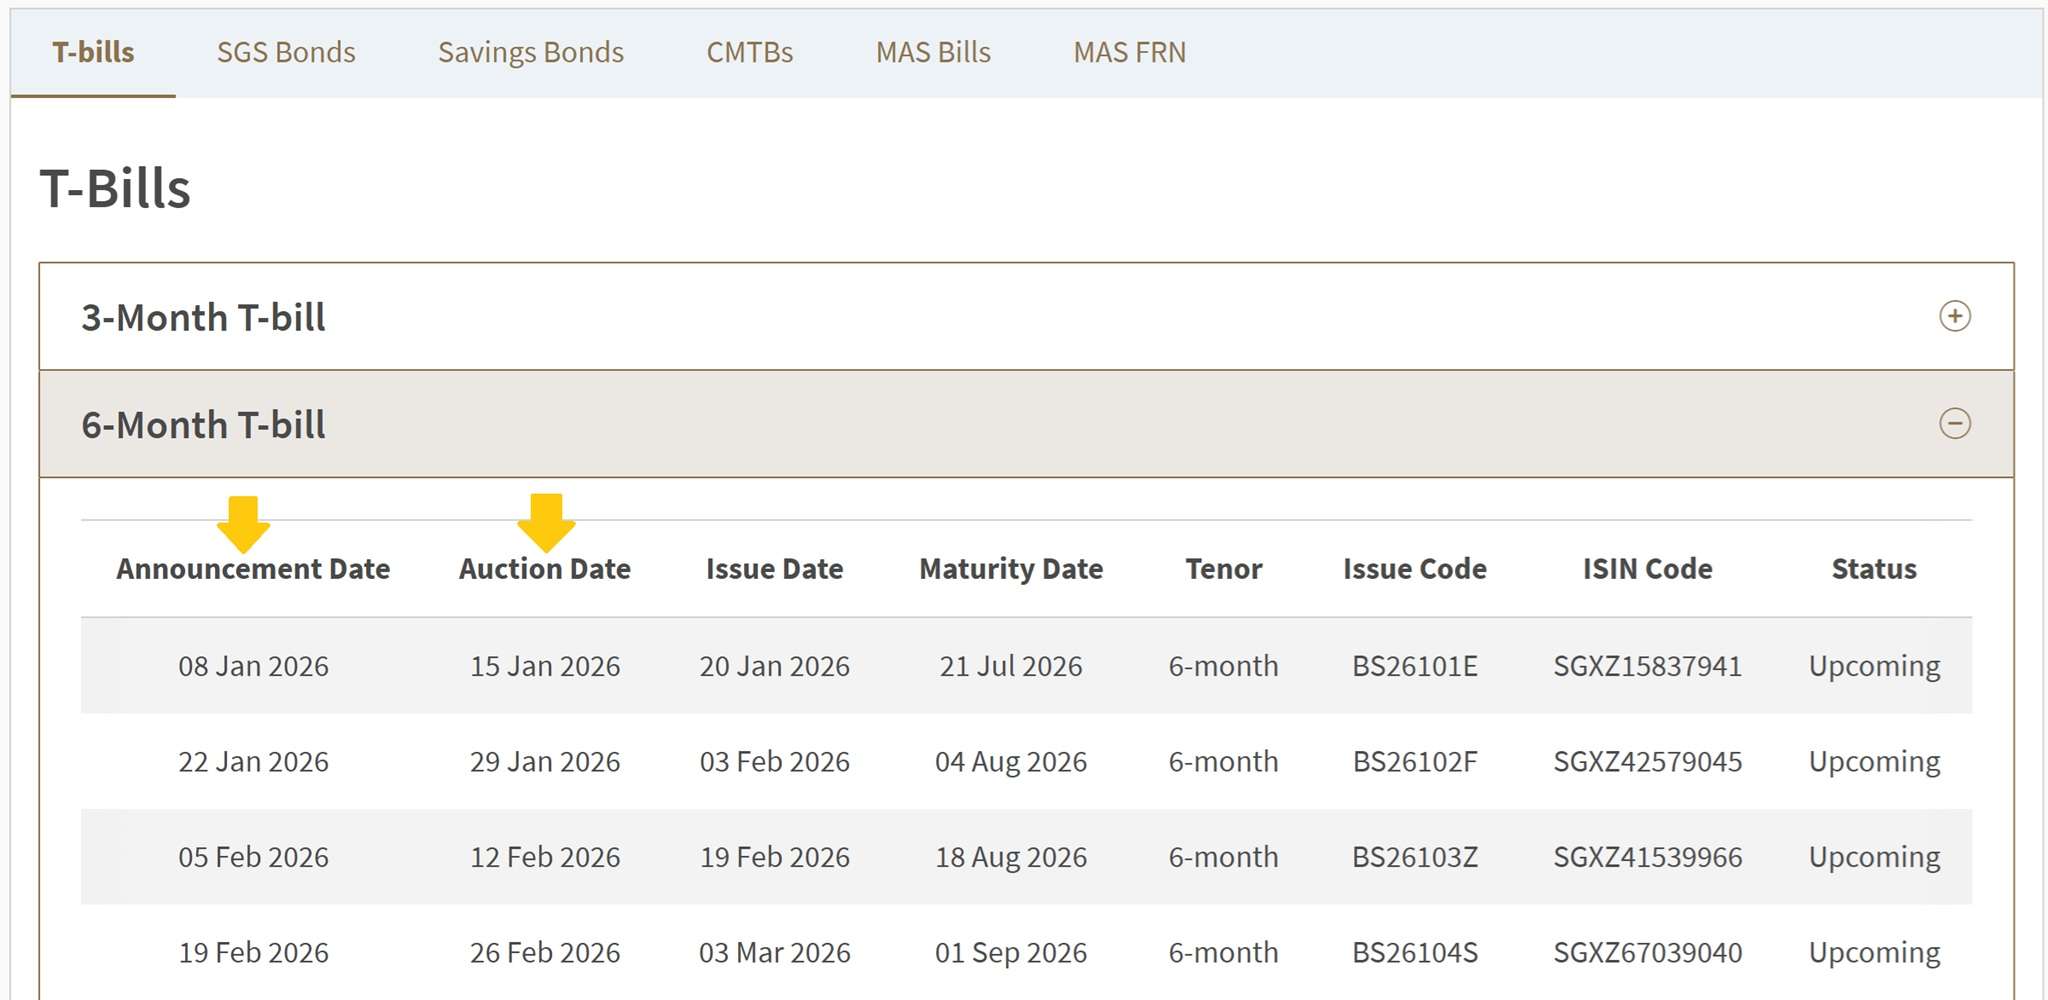
Singapore Treasury Bills can be purchased with cash, CPF Ordinary Account funds, or SRS savings. You apply through internet banking with DBS, OCBC, or UOB, or at an ATM. Applications must be submitted before each bank’s cut-off time, typically one business day before the auction.
When applying, you choose between a competitive bid (you specify the yield you’re willing to accept) or a non-competitive bid (you accept whatever cut-off yield the auction determines). T-Bills are issued at a discount, so you pay less upfront and receive the full face value at maturity, either 6 months or 1 year later depending on the tenor.
Key auction dates are published on the MAS Auctions and Issuance Calendar. One important update for CPF users: since late 2024, CPF Special Account (SA) funds can no longer be used for new SGS Bond or T-Bill applications, as the SA is being phased out for members aged 55 and above. CPF Ordinary Account (OA) funds remain usable via CPFIS. I also track my own T-Bill holdings alongside my stocks and Singapore Savings Bonds using Stocks Café, which lets you organise separate portfolios for each asset type.
Latest Treasury Bill Posts
T Bill Singapore BS26107X is 1.47%

T Bill Singapore BY26100S is 1.44%
BS25125Z 6-Month T-bill is 1.48%
SGS T Bills Singapore BS25111T is 2.05%
SGS T Bills Singapore BY25100H is 2.95%
T Bills Singapore BS24121A is 2.99%
Frequently Asked Questions
Are Singapore Treasury Bills safe?
Yes. Singapore Treasury Bills are backed by the Singapore government, which holds one of the highest sovereign credit ratings in the world (AAA from all three major rating agencies). They are widely considered one of the safest instruments available to retail investors in Singapore, on par with Singapore Savings Bonds. Interest earned is also not taxed for individual investors, the same treatment as SSBs and fixed deposits.
What happens if I need my money before the T-Bill matures?
Unlike Singapore Savings Bonds, T-Bills cannot be redeemed early. However, you can sell your T-Bill in the secondary market through your broker before maturity, though the price you receive will depend on prevailing market rates at the time and may be more or less than what you paid.
Can I apply for T-Bills using CPF or SRS funds?
Yes, T-Bills can be purchased with cash, CPF Ordinary Account funds, or SRS savings, giving you flexibility depending on which pool of money you want to put to work at short-term government rates.