Table of Contents
Frasers Centrepoint Trust 2HFY26 financial results showcased another year of resilient performance, with the Singapore suburban retail REIT delivering record distributions, healthy rental growth and continued progress on key growth initiatives. The latest results reinforce why Frasers Centrepoint Trust remains one of the strongest retail REITs listed on the Singapore Exchange.
As an investor, Frasers Centrepoint Trust currently makes up 8.11% of my stock portfolio based on the amount invested. With the Frasers Centrepoint Trust Share Price trading at S$2.17, many income-focused investors will be reviewing the latest numbers to determine whether the REIT remains attractive for long-term dividend investing.
The latest results highlight record distributions, strong portfolio occupancy, positive rental reversions, active asset enhancement initiatives and prudent capital management. Collectively, these factors continue to support future growth in the Frasers Centrepoint Trust dividend while providing stability for the Frasers Centrepoint Trust share price.
Frasers Centrepoint Trust 2HFY26 Financial Results at a Glance
The key highlight was the achievement of a record Distribution Per Unit (DPU).
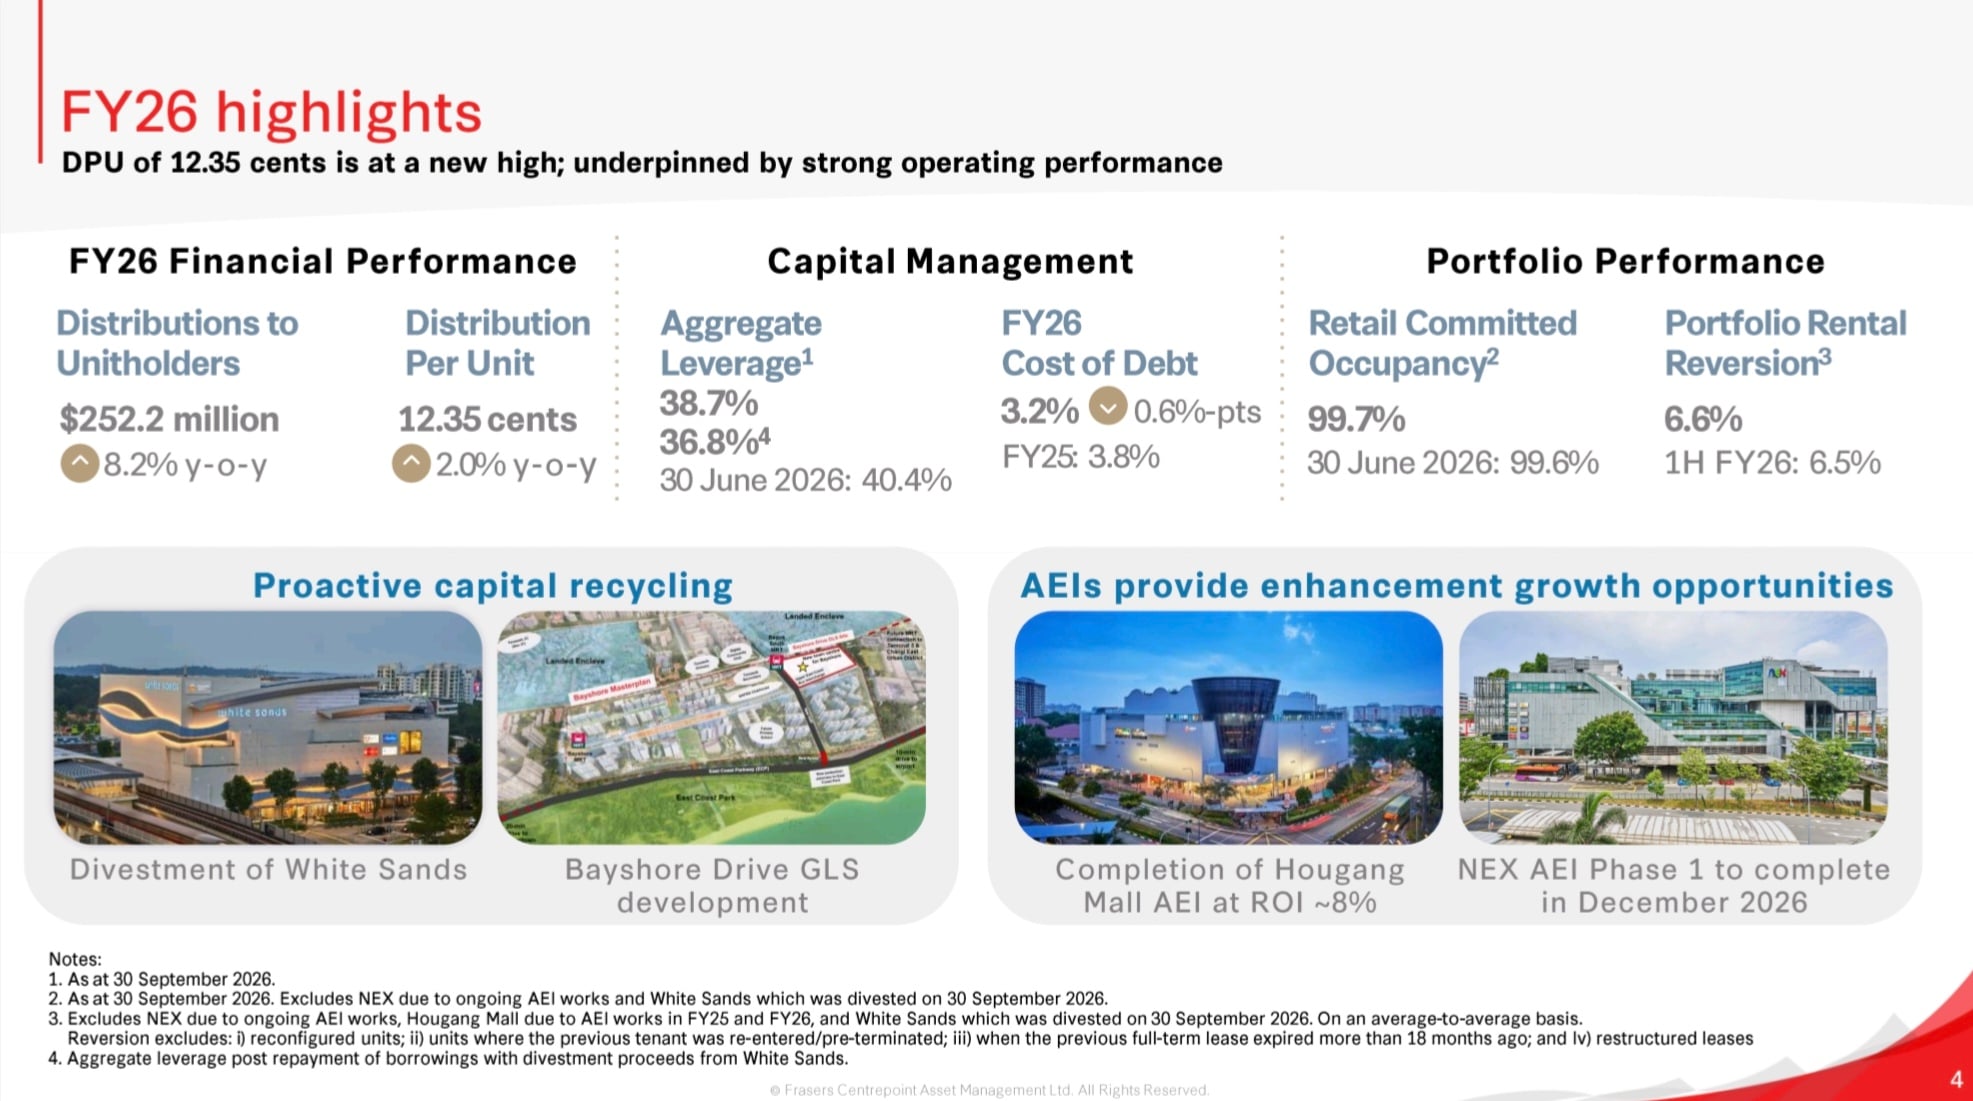
For 2HFY26, DPU increased to 6.214 cents, compared with 6.059 cents in the same period a year earlier. On a full-year basis, DPU reached 12.35 cents, representing the highest annual distribution since the REIT’s listing in 2006.
Frasers Centrepoint Trust also saw strong growth across key operating metrics. Gross revenue for the second half grew 8.7% year-on-year to S$223.0 million, while net property income rose 11.5% to S$160.9 million. Distributions to unitholders increased by 3.3% year-on-year to S$127.2 million.
For the full financial year, gross revenue increased 14.2% to S$444.9 million, while net property income climbed 15.7% to S$321.7 million. Distributions to unitholders increased by 8.2% to S$252.2 million.
These numbers demonstrate that Frasers Centrepoint Trust 2HFY26 Financial Results were supported by both acquisition-driven growth and organic growth from the existing portfolio.
Record Frasers Centrepoint Trust Dividend Continues to Impress
Income investors typically focus on distributions first, and the latest Frasers Centrepoint Trust dividend did not disappoint.
The full-year Frasers Centrepoint Trust dividend increased to 12.35 cents per unit from 12.113 cents previously. Although headline growth was modest at 2.0%, investors should note that management retained a portion of distributable income for asset enhancement initiatives and working capital purposes.
The ability to maintain and increase the Frasers Centrepoint Trust dividend even while investing for future growth demonstrates the quality of the underlying assets. For long-term investors seeking passive income, a steadily rising Frasers Centrepoint Trust dividend is more important than short-term fluctuations.
The payment details announced under the Frasers Centrepoint Trust 2HFY26 Financial Results indicate that the 2HFY26 DPU of 6.214 cents will be paid on 27 November 2026.
Looking ahead, the sustainability of the Frasers Centrepoint Trust dividend appears well supported by healthy occupancy levels, positive rental reversions and ongoing enhancement projects across the portfolio.
Frasers Centrepoint Trust Share Price and Valuation
The current Frasers Centrepoint Trust Share Price stands at S$2.17. Following the release of the Frasers Centrepoint Trust 2HFY26 Financial Results, investors may be evaluating whether the REIT remains fairly valued.
One useful benchmark is the REIT’s net asset value. As at 30 September 2026, net asset value per unit was S$2.32 while adjusted net asset value per unit stood at S$2.25.
Based on these figures, the Frasers Centrepoint Trust share price is trading below both NAV and adjusted NAV.
The Frasers Centrepoint Trust Share Price is supported by a quality portfolio of suburban malls including Causeway Point, Northpoint City, Tampines 1, Hougang Mall, Century Square, Tiong Bahru Plaza, NEX and Waterway Point. These assets are located within densely populated residential catchments and enjoy recurring shopper traffic.
Given the strength shown in the Frasers Centrepoint Trust 2HFY26 Financial Results, investors may view the current Frasers Centrepoint Trust share price as offering a combination of income and long-term growth potential.
Portfolio Occupancy Remains Near Full Capacity
Another standout feature of the Frasers Centrepoint Trust Financial Results was the portfolio’s exceptionally high occupancy rate.
Retail committed occupancy stood at 99.7% as at 30 September 2026. Such occupancy levels are among the strongest across the Singapore REIT sector and demonstrate the attractiveness of the portfolio to tenants.
High occupancy is important because it supports stable rental income and provides visibility for future Frasers Centrepoint Trust dividend payments.
The operating performance remains encouraging. Shopper traffic increased by 1.8% year-on-year and tenants’ sales grew by 1.3% year-on-year. The ability to maintain positive retail activity despite a challenging consumer environment reflects the resilience of suburban retail assets.
As a result, the fundamentals supporting the Frasers Centrepoint Trust share price remain healthy.
Healthy Rental Reversions Support Future Growth
Rental growth remains one of the most important drivers behind the Frasers Centrepoint Trust Financial Results.
The retail portfolio achieved rental reversion of 6.6% during FY2026, while tenant retention remained at 81%. This indicates that existing tenants are willing to renew leases at higher rental rates, reflecting healthy demand for space within the portfolio.
Positive rental reversions provide a source of organic growth without requiring major acquisitions. This supports future increases in the Frasers Centrepoint Trust dividend and provides a positive foundation for long-term growth in cash flow.
The robust leasing environment also supports confidence in the Frasers Centrepoint Trust Share Price as rental income continues to trend upwards.
Asset Enhancement Initiatives Continue to Create Value
Asset enhancement initiatives remain an important component of the Frasers Centrepoint Trust growth strategy.
The Hougang Mall enhancement project was completed in September 2026 and achieved committed occupancy of 99.7%. The project delivered an estimated return on investment of around 8%, exceeding initial expectations.
The NEX asset enhancement initiative remains on track, with Phase 1 expected to be completed by the end of 2026. Meanwhile, Causeway Point is preparing for a major transformation that is expected to commence in the second quarter of 2027.
These projects are designed to enhance tenant mixes, improve shopper experiences and drive future rental growth. Over time, successful execution should strengthen both the Frasers Centrepoint Trust dividend and the Frasers Centrepoint Trust share price.
Capital Recycling Unlocks New Opportunities
Frasers Centrepoint Trust results also highlighted management’s disciplined approach to capital allocation.
During FY2026, White Sands was divested for S$467 million, representing an 8.4% premium to its appraised value. The transaction unlocked capital which can be redeployed into future growth opportunities.
Part of the proceeds has been invested into the Bayshore Drive development project. The development is expected to become the only retail destination within a rapidly growing residential precinct and is estimated to generate an attractive yield on cost of approximately 5%.
This project also creates a future acquisition pipeline that may contribute to sustained growth in the Frasers Centrepoint Trust dividend.
Balance Sheet Remains Healthy
The strength of a REIT ultimately depends on its balance sheet, and the Frasers Centrepoint Trust 2HFY26 Financial Results revealed a healthy financial position.
Aggregate leverage stood at 38.7% as at 30 September 2026. Management indicated that leverage would fall further to 36.8% following debt repayment using divestment proceeds from White Sands.
Interest coverage ratio improved to 4.37 times, while the average cost of debt declined to 3.2% compared with 3.8% in the previous year.
The REIT also maintains substantial undrawn facilities and has no refinancing risk in FY2027. These factors reduce financial risk and enhance the sustainability of future Frasers Centrepoint Trust dividend payments.
A stronger balance sheet also provides additional support for the Frasers Centrepoint Trust Share Price during periods of market volatility.
My Thoughts on Frasers Centrepoint Trust 2HFY26 Financial Results
The REIT delivered record distributions, maintained exceptionally high occupancy, achieved healthy rental reversions, improved its balance sheet and continued investing for future growth. These qualities are precisely what I look for in a long-term income-generating REIT.
As mentioned earlier, Frasers Centrepoint Trust accounts for 8.11% of my stock portfolio based on the total amount invested. The strength of the Frasers Centrepoint Trust 2HFY26 Financial Results reinforces my confidence in the REIT’s ability to continue generating sustainable distributions.
At a Frasers Centrepoint Trust Share Price of S$2.17, investors are gaining exposure to high-quality suburban retail assets that continue to benefit from necessity-driven spending, strong residential catchments and limited future suburban retail supply.
While risks remain, including economic uncertainty and execution risks associated with development projects, the overall outlook for the Frasers Centrepoint Trust dividend remains favourable based on the latest financial performance.
Pros and Cons of Investing in Frasers Centrepoint Trust
Pros
- Record Frasers Centrepoint Trust dividend of 12.35 cents per unit for FY2026.
- Retail portfolio committed occupancy remains exceptionally strong at 99.7%.
- Healthy rental reversion of 6.6% supports future revenue growth.
- Gross revenue and net property income recorded double-digit growth.
- Strong balance sheet with improving interest coverage ratio and lower borrowing costs.
- Asset enhancement initiatives provide additional organic growth opportunities.
- Capital recycling strategy successfully unlocked value through the White Sands divestment.
Cons
- Growth in Frasers Centrepoint Trust dividend remains relatively modest despite strong operational performance.
- Ongoing asset enhancement projects may temporarily affect mall operations.
- Retail REITs remain exposed to changes in consumer spending patterns.
- Aggregate leverage remains close to 40%, although management expects further reductions.
- Bayshore Drive development introduces execution and development risks.
- Future interest rate movements could still affect financing costs and distributions.