Table of Contents
OUE REIT 3Q 2026 business result demonstrates how the REIT is successfully balancing income growth, capital recycling and portfolio optimisation despite ongoing tenant transitions within its office portfolio.
According to the latest quarterly update, OUE REIT reported higher revenue, stronger net property income, lower finance costs and continued positive rental reversions across its key assets. As a unitholder, I found the latest OUE REIT 3Q 2026 business result encouraging as management continues to execute its Phase 3 Value Creation strategy.
For transparency, OUE REIT currently makes up 1.60% of my stock portfolio based on the amount invested.
OUE REIT 3Q 2026 Business Result Overview
The headline numbers from the OUE REIT 3Q 2026 business result were largely positive.
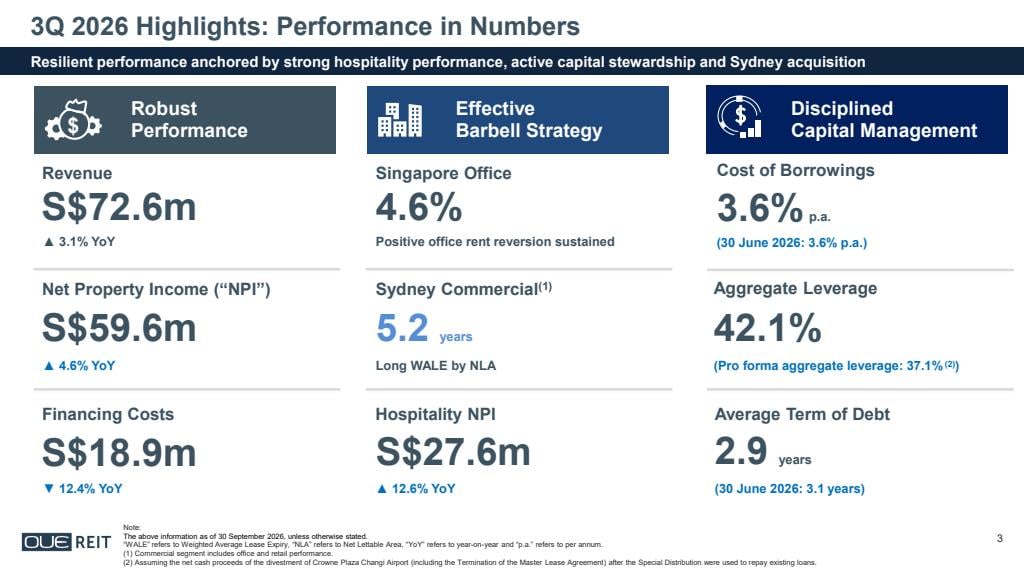
Revenue increased 3.1% year-on-year to S$72.6 million while net property income rose 4.6% year-on-year to S$59.6 million. The stronger growth in net property income compared to revenue indicates healthy operational efficiency and disciplined expense management.
One of the standout achievements during the quarter was the 12.4% year-on-year reduction in finance costs. In a higher-rate environment over the past few years, many REITs have struggled with rising borrowing expenses. OUE REIT’s proactive refinancing efforts and disciplined capital management have started to bear fruit.
The REIT also received a contribution from its recently acquired 19.9% stake in 180 George Street, Sydney. The investment generated S$1.6 million in distribution income during the quarter and provides an additional source of recurring income.
From a portfolio perspective, the OUE REIT 3Q 2026 business result highlights the benefits of having diversified exposure across office, hospitality and retail properties.
Hospitality Segment Continues To Lead Growth
The hospitality business was the strongest contributor in the OUE REIT 3Q 2026 business result.
Hospitality revenue increased 12.6% year-on-year to S$30.3 million while hospitality net property income also climbed 12.6% to S$27.6 million.
The strong performance was driven by rising leisure travel demand, growth in corporate bookings and refreshed guest offerings across its hospitality assets.
Revenue per available room, or RevPAR, increased 8.2% year-on-year to S$302. Hilton Singapore Orchard recorded a 7.5% increase in RevPAR supported by stronger occupancy, resilient travel demand and successful corporate account acquisitions.
This remains an important pillar supporting future OUE REIT dividend sustainability. Singapore continues to benefit from major international events, conferences, concerts and tourism-related activities. Management also highlighted that hotel supply growth is expected to remain relatively modest between 2026 and 2028, creating a favourable environment for hotel operators.
For income investors, hospitality remains an increasingly important earnings driver behind the OUE REIT dividend outlook.
Singapore Office Portfolio Remains Resilient
While hospitality delivered strong growth, the commercial portfolio experienced some near-term softness.
Commercial segment revenue declined 2.8% year-on-year to S$42.4 million while net property income slipped 1.5% to S$32.0 million. The decline was largely attributed to tenant transition activities at OUE Downtown Office.
Despite the softer revenue contribution, Singapore office fundamentals remained healthy.
Office rental reversion remained positive at 4.6% during the quarter. Committed occupancy was stable at 91.2% and average passing rent remained at S$11.06 per square foot per month.
Management has been taking a longer-term approach to improving tenant quality and lease profile. Deloitte extended more than 49,000 square feet of office space until the fourth quarter of 2027. This gives management greater flexibility in executing its tenant rejuvenation strategy.
The broader Singapore office market remains supportive. Core CBD Grade A office occupancy reached 97.4% while rents rose to S$12.75 per square foot per month. With limited new supply expected before 2028, landlords continue to enjoy favourable conditions.
Although office occupancy may remain moderated over the next 12 to 15 months, the long-term outlook remains constructive based on the current supply-demand dynamics.
Mandarin Gallery Delivers Stable Performance
Mandarin Gallery recorded another quarter of steady performance.
Rental reversion came in at 5.9% during the quarter while committed occupancy improved by 2 percentage points to 96.7%. Average passing rent remained healthy at S$22.94 per square foot per month.
Orchard Road retail conditions remain competitive, but prime retail rents continue to show resilience. Management’s efforts to refresh its tenant mix and improve shopper engagement appear to be producing results.
The retail segment may not be the largest contributor to earnings, but it provides another layer of diversification and stability to support future OUE REIT dividend payments.
180 George Street Adds Another Quality Income Stream
One of the more interesting developments in the OUE REIT 3Q 2026 business result was the growing contribution from 180 George Street in Sydney.
The premium office asset generated S$1.6 million in distribution income during the quarter.
As of 30 September 2026, the property was fully committed and enjoys a weighted average lease expiry of 4.8 years by gross rental income.
The Sydney office market also continues to improve. Premium office assets remain beneficiaries of the ongoing flight-to-quality trend, where tenants increasingly prefer higher quality and more sustainable office buildings.
Over time, this investment could improve portfolio resilience while reducing concentration risk in Singapore.
Balance Sheet Strength Continues To Improve
Another highlight of the OUE REIT 3Q 2026 business result was the continued improvement in capital management.
Weighted average cost of debt remained stable at 3.6%, while finance costs declined 12.4% year-on-year.
Interest coverage ratio improved to 2.9 times while debt maturities remained well distributed across multiple years.
Aggregate leverage stood at 42.1% as at 30 September 2026. While this remains elevated compared to some peers, management expects leverage to decline significantly after the completion of the Crowne Plaza Changi Airport divestment.
Assuming the divestment proceeds are used to repay debt, aggregate leverage could decline to 37.1%, providing substantial debt headroom for future growth opportunities.
The REIT also secured a new unsecured committed revolving credit facility of up to S$300 million, strengthening liquidity and enhancing financial flexibility.
These developments are positive for future OUE REIT dividend sustainability because lower debt and lower financing costs translate into stronger distributable income.
Crowne Plaza Changi Airport Divestment Is A Major Catalyst
The biggest strategic move highlighted in the OUE REIT 3Q 2026 business result remains the divestment of Crowne Plaza Changi Airport.
The transaction is expected to complete on 30 October 2026.
Management expects to unlock approximately S$498.5 million in net proceeds. These funds may be deployed toward debt reduction, new investments and other value-enhancing initiatives.
More importantly for income investors, management expects a S$20 million special distribution to commence from FY2027.
This creates the possibility of an enhanced OUE REIT dividend over the next two years while management executes its capital recycling strategy.
Investors should continue monitoring how management redeploys these proceeds because future returns will largely depend on whether the capital is invested into accretive opportunities.
My Thoughts On OUE REIT 3Q 2026 Business Result
Overall, I believe the OUE REIT 3Q 2026 business result was encouraging.
The hospitality segment continues to perform strongly, rental reversions remain positive, finance costs are falling and the balance sheet is gradually improving.
At the same time, management continues to recycle capital through divestments and reinvestment opportunities. The contribution from 180 George Street demonstrates that management is actively looking for ways to strengthen portfolio quality and diversify income sources.
There are still some short-term risks. Office occupancy may remain under pressure while tenant transitions continue, and investors will be closely watching how management deploys the Crowne Plaza Changi Airport divestment proceeds.
However, based on the latest OUE REIT 3Q 2026 business result, the REIT appears well-positioned to continue delivering stable income and potentially stronger distributions over the medium term.
As someone with OUE REIT accounting for 8.07% of my stock portfolio, I remain optimistic about the long-term outlook while keeping a close eye on execution risks associated with the ongoing portfolio transition.
Pros And Cons Of Investing In OUE REIT Now
- Pros
- Revenue increased 3.1% year-on-year while net property income increased 4.6% year-on-year.
- Hospitality revenue and net property income both grew 12.6% year-on-year.
- Positive office rental reversion of 4.6% despite tenant transitions.
- Finance costs declined 12.4% year-on-year.
- 180 George Street provides a new recurring income stream.
- Potential leverage reduction from 42.1% to 37.1% after the hotel divestment.
- S$20 million special distribution expected from FY2027, supporting future OUE REIT dividend potential.
- Singapore office market fundamentals remain favourable due to limited new supply.
- Cons
- Commercial segment revenue and NPI declined because of tenant transition activities.
- Near-term office occupancy may remain moderated over the next 12 to 15 months.
- Aggregate leverage remains relatively high at 42.1% before divestment proceeds are deployed.
- Future earnings growth depends on successful redeployment of divestment proceeds.
- Hospitality performance remains exposed to tourism and economic conditions.