Table of Contents
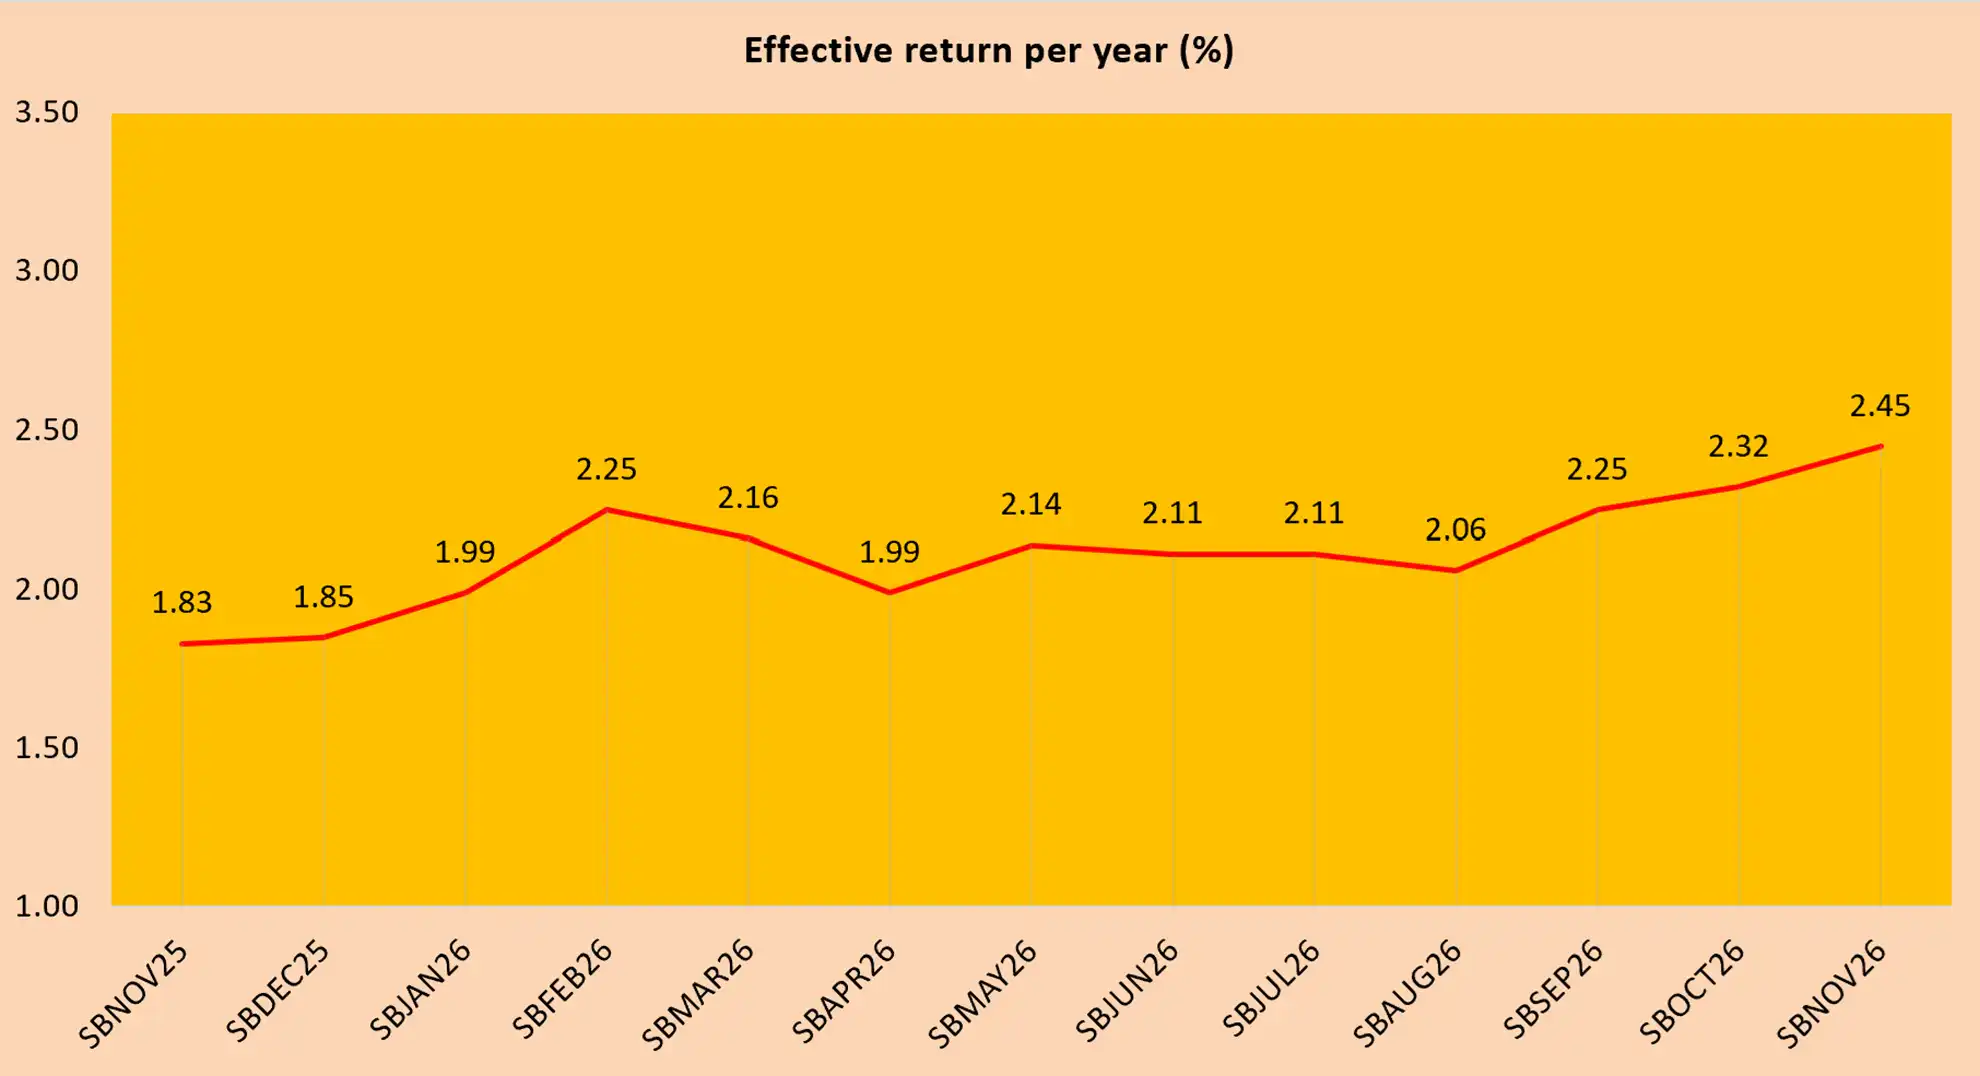
The November 2026 Singapore Savings Bond (SBNOV26 GX26110X) offers a 10-year average return of 2.45% p.a., up from 2.32% on the October issue. This marks the third consecutive monthly rise, continuing a gradual recovery in SSB rates over the past few months.
When it comes to building a stable foundation for my portfolio, Singapore Savings Bonds naturally stand out. They are designed to be low risk, especially when compared with more volatile investments like individual stocks or ETFs.
For anyone who values capital preservation and peace of mind, the Singapore Savings Bond can serve as a reliable anchor. It may not deliver the explosive gains that equities sometimes offer, but it also avoids the same level of uncertainty.
What is a Singapore Savings Bond?
A Singapore Savings Bond, or SSB, is a special type of Singapore Government Security designed for individual investors who want a safe and flexible way to grow their savings.
Unlike many traditional bonds, a Singapore Savings Bond does not require investors to sell it in the open market if they want to exit early. Instead, redemption is done through MAS, and the money is typically returned within the following month. This makes SSBs useful for investors who want both safety and flexibility, especially when comparing them with fixed deposits, Treasury bills, or savings accounts.
Minimum investment amount for Singapore Savings Bonds
The minimum investment amount for a Singapore Savings Bond is just S$500, which makes it easy to start small and build a position gradually. This low entry point is useful for new investors who want to get comfortable with government bonds, as well as for experienced investors looking to park spare cash in a safe, interest-bearing instrument. With SBNOV26 GX26110X, it also makes sense to compare the SSB interest rate against fixed deposits, Treasury bills and high-yield savings accounts before applying.
Each individual can invest up to S$200,000 in Singapore Savings Bonds, inclusive of both cash and SRS contributions. The longer you hold an SSB, the higher your effective return can become, thanks to the step-up interest feature. This structure rewards patience and disciplined saving, which is exactly the kind of habit I have been trying to build over the years.
Who is this SSB suitable for?
SBNOV26 GX26110X may be suitable for investors who prefer stability over higher-risk returns. It can appeal to conservative investors, retirees, near-retirees, and anyone who wants to preserve capital while still earning a predictable return. Because the Singapore Savings Bond can be redeemed monthly without penalty, it may also work well for people who want to park spare cash while keeping access to their funds.
This SSB may also be useful for investors who are building an emergency fund, planning for retirement, or balancing a portfolio that already has exposure to stocks, ETFs or REITs. While the SSB interest rate may not always be higher than fixed deposit promotions or Treasury bill yields, the combination of government backing, step-up returns and redemption flexibility make it a practical option for long-term savers.
SBNOV26 GX26110X Interest Rate Table
According to MAS, here is the full step-up schedule for this issue:
| Year from Issue | Interest Rate | Average Return Per Year |
| 1 | 1.67% | 1.67% |
| 2 | 2.00% | 1.83% |
| 3 | 2.19% | 1.95% |
| 4 | 2.35% | 2.05% |
| 5 | 2.49% | 2.13% |
| 6 | 2.61% | 2.21% |
| 7 | 2.70% | 2.27% |
| 8 | 2.79% | 2.33% |
| 9 | 2.91% | 2.39% |
| 10 | 3.08% | 2.45% |
If you invest S$10,000 in this SSB and hold it for the full 10 years, you will earn a total of roughly S$2,478.54 in interest, based on the step-up schedule above.
Issue Details
- Issue code: GX26110X (SBNOV26)
- Amount offered: S$400 million
- Opening date: 1 October 2026, 6pm
- Closing date: 27 October 2026, 9pm
- Allotment date: 28 October 2026
- Issue date: 2 November 2026
- Maturity date: 1 November 2036
- Interest payment dates: Every 6 months, on 1 May and 1 November
How SBNOV26 GX26110X Compares to Recent Issues
This is the third month in a row that SSB rates have climbed, up from 2.25% on the September issue and 2.32% on the October issue. The 10-year average of 2.45% is the highest since July 2025. Since SSB coupon rates are set from the average Singapore Government Securities yields of the previous month, the November rates reflect where SGS yields traded through September 2026.
Worth keeping in perspective: SSB rates were considerably higher from late 2022 through 2024, so while the recent upward trend is encouraging, this issue still sits below what investors could lock in during that earlier period. See my T Bills Singapore guide if you want to compare against current T-bill yields, which tend to move independently of the SSB step-up schedule.
How to Apply
Applications can be made through DBS/POSB, OCBC, or UOB internet banking, mobile apps, or ATMs, using cash, or through your CPF Ordinary Account (CPFIS-OA) or SRS account. The minimum application is S$500, in multiples of S$500, with a per-tranche cap of S$200,000 per individual. Applications for SBNOV26 close at 9pm on 27 October 2026.
SBNOV26 GX26110X FAQ
What is the interest rate for SBNOV26 GX26110X?
1.67% in year one, stepping up to 3.08% by year ten, averaging 2.45% p.a. if held for the full 10 years.
When does SBNOV26 GX26110X close for applications?
Applications close at 9pm on 27 October 2026, with allotment results announced on 28 October 2026.
Can I redeem SBNOV26 GX26110X before 10 years?
Yes. Like all Singapore Savings Bonds, SBNOV26 can be redeemed in any month with no penalty, receiving the full principal plus accrued interest up to that point.
Is SBNOV26 GX26110X a good rate compared to recent months?
Yes, relatively. It is the third consecutive monthly increase and the highest 10-year average since July 2025, though still below the peak rates seen in 2022 to 2024.
Disclaimer: This is not a sponsored post, and the opinions are solely based on My Sweet Retirement’s own research. Figures are sourced from MAS’s official Singapore Savings Bonds issuance data for GX26110X. Rates and terms are correct as of time of writing and subject to MAS’s official confirmation; always verify directly on the MAS Singapore Savings Bonds page before applying.